Sample report
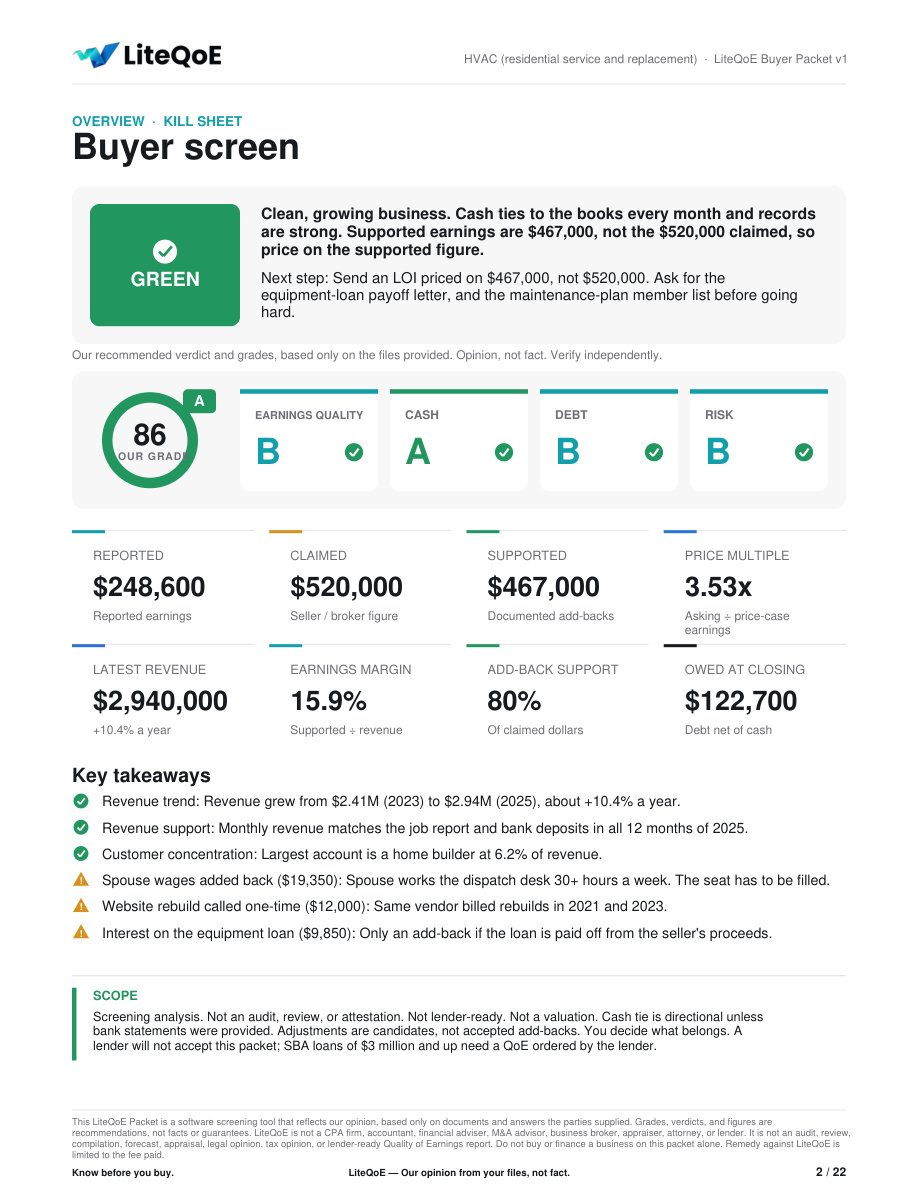
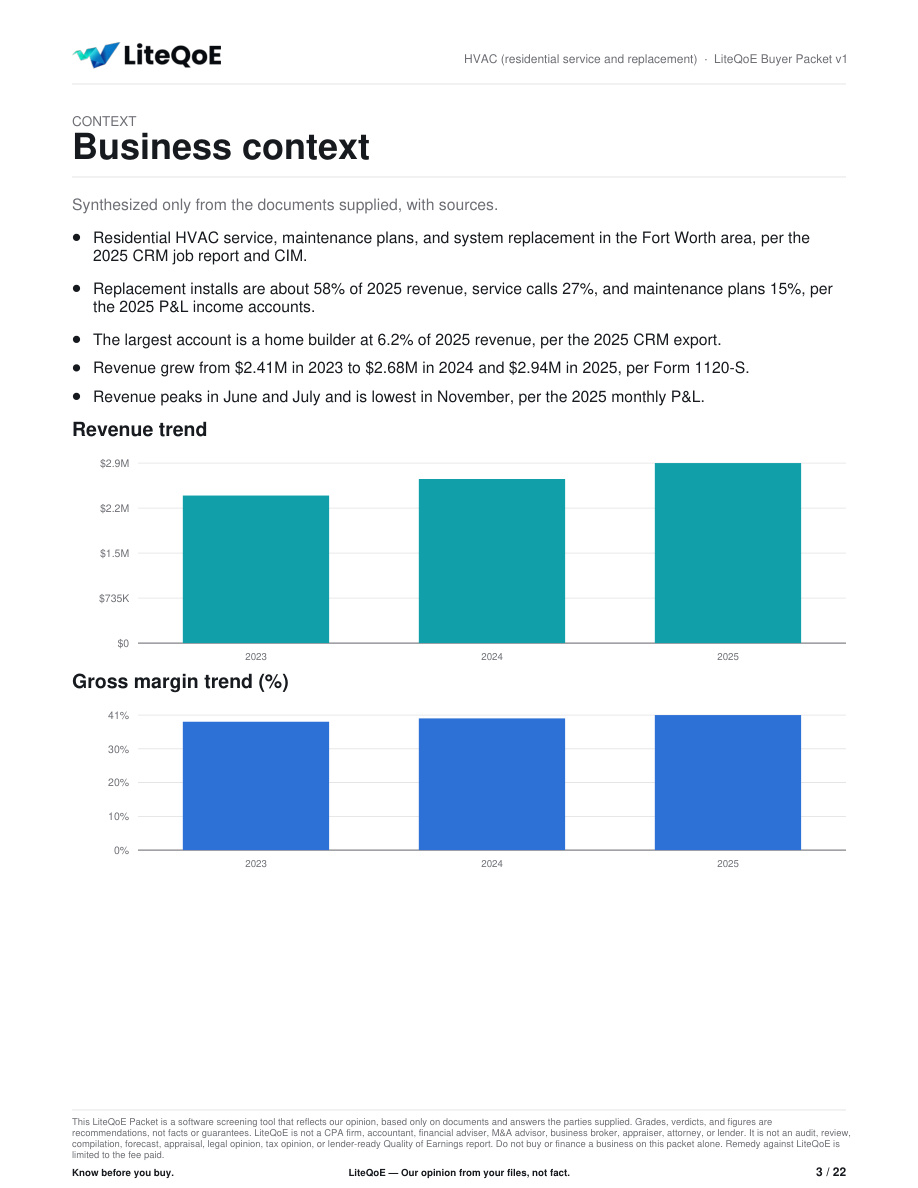
A fictional business, for illustration only.
Download PDF
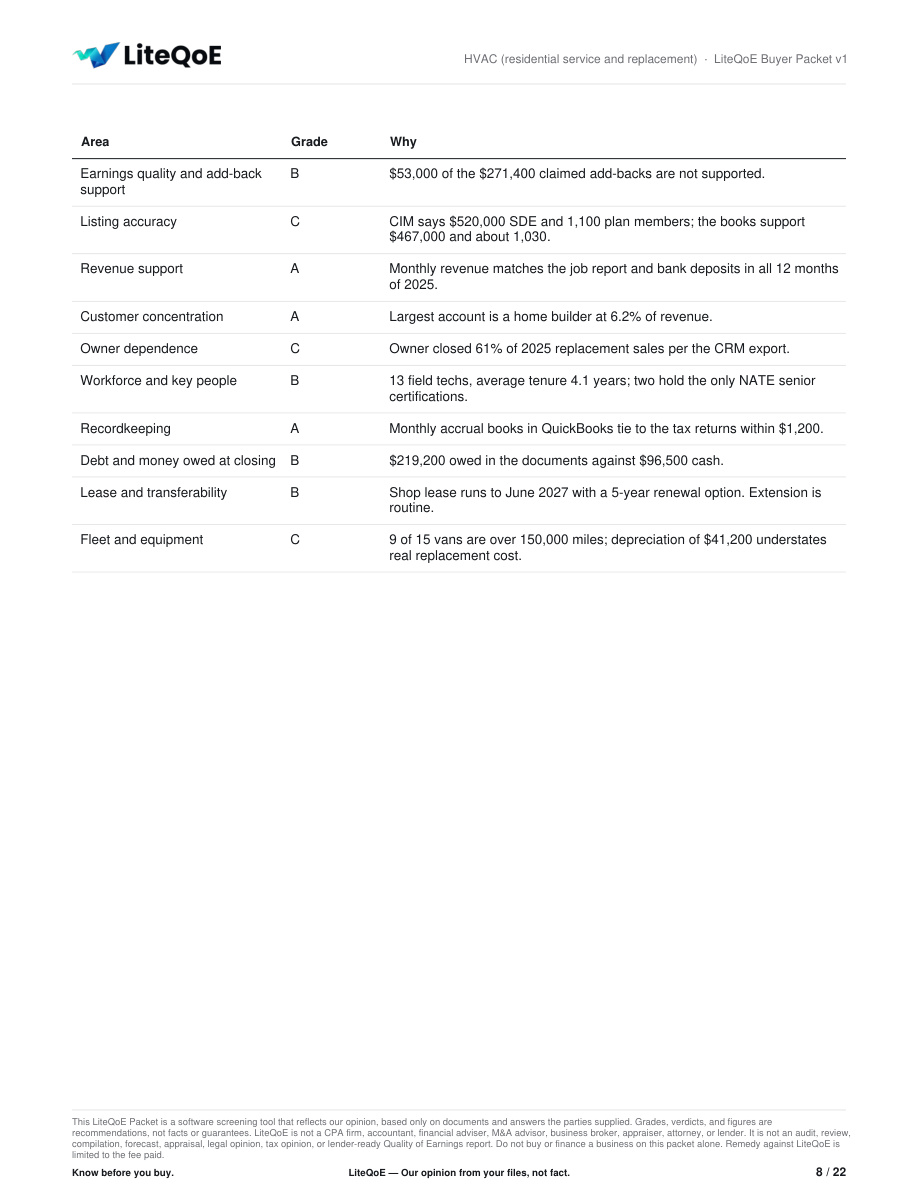
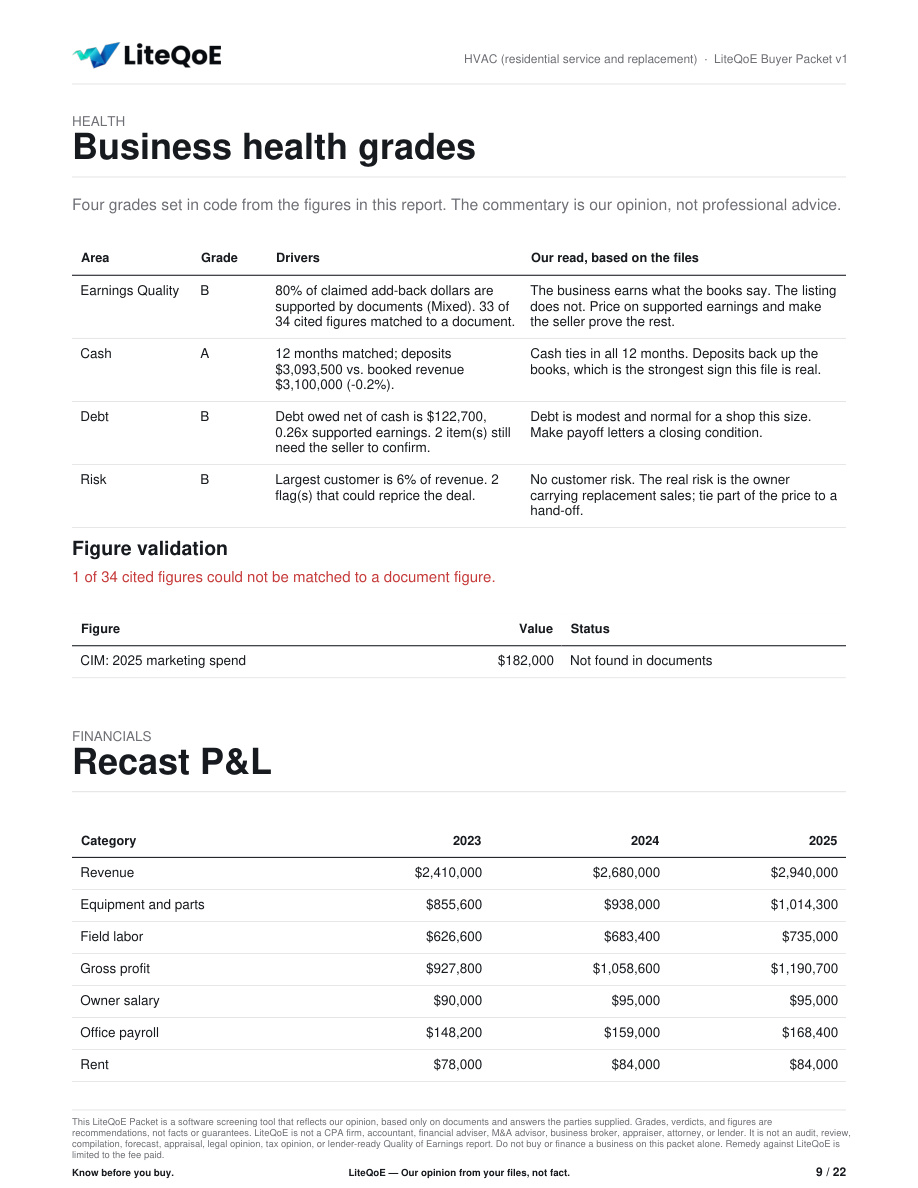
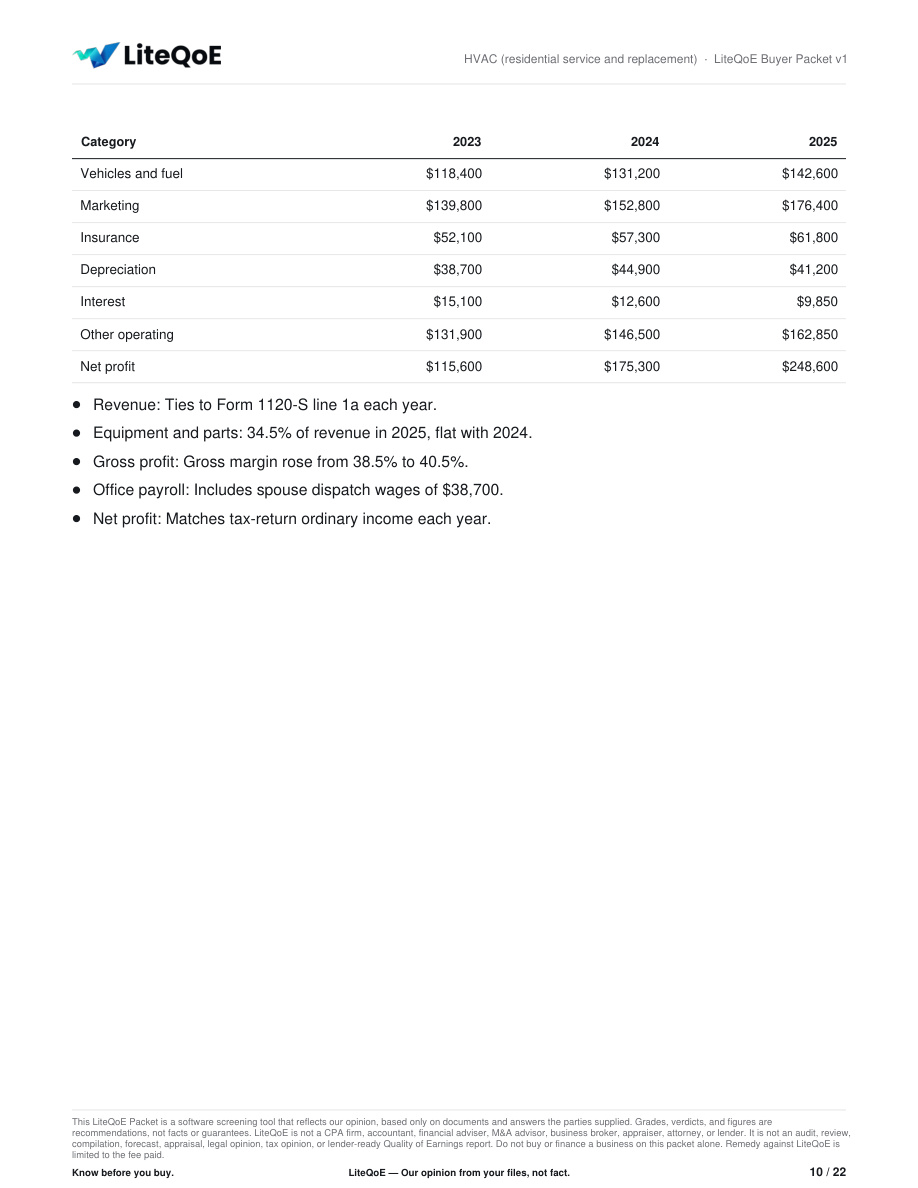
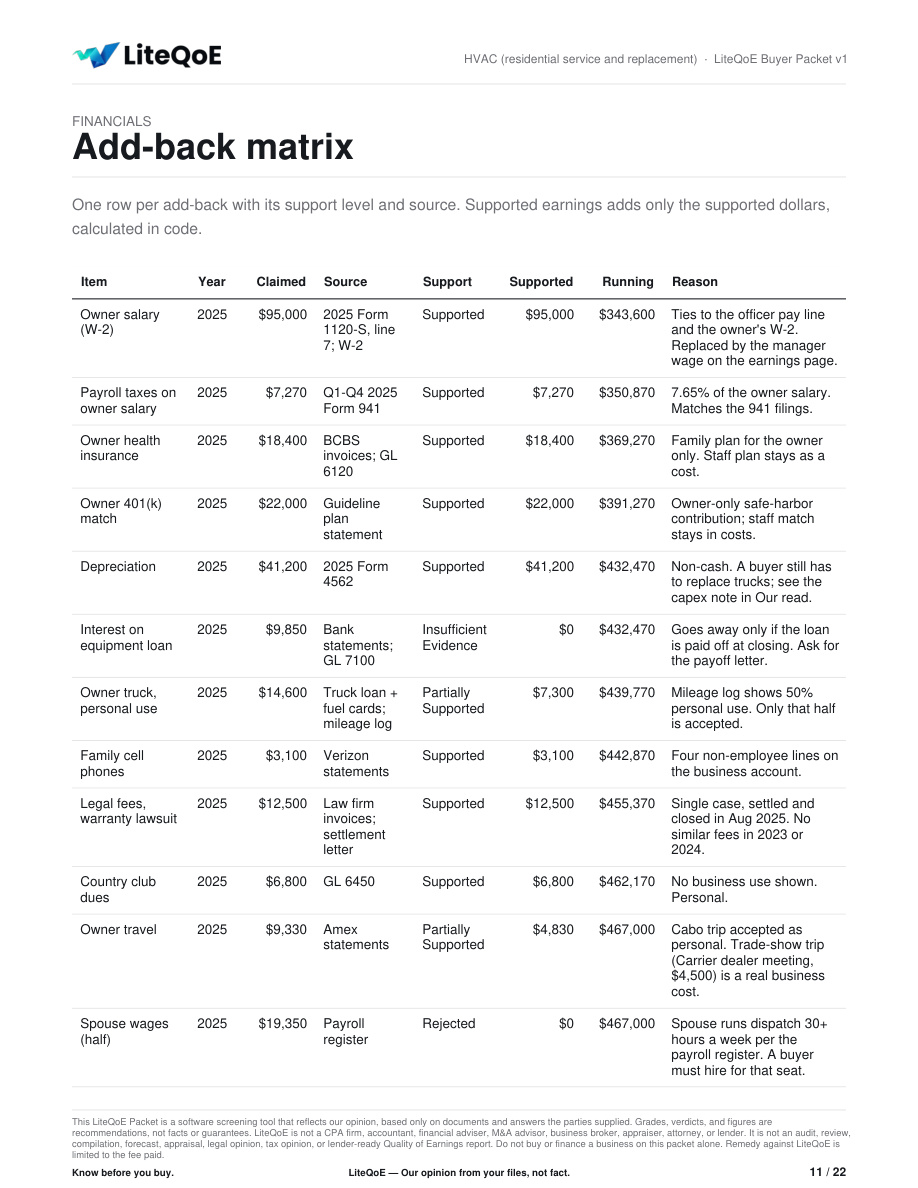
Sample closing timeline add-on ($79)
Written for each deal from its screen and the buyer's financing plan. Fictional business, for illustration only.
Closing timeline — Sample HVAC services
Expected length: 12-16 weeks
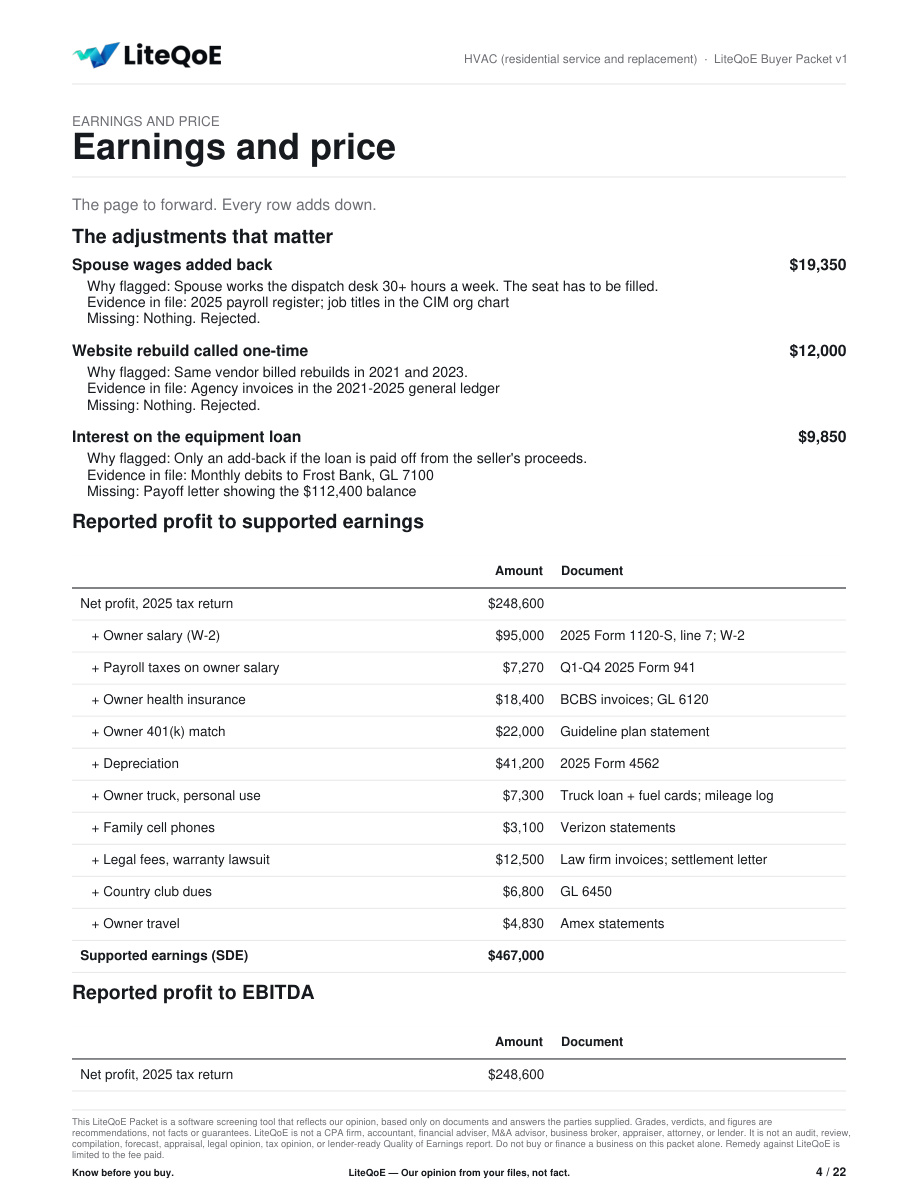
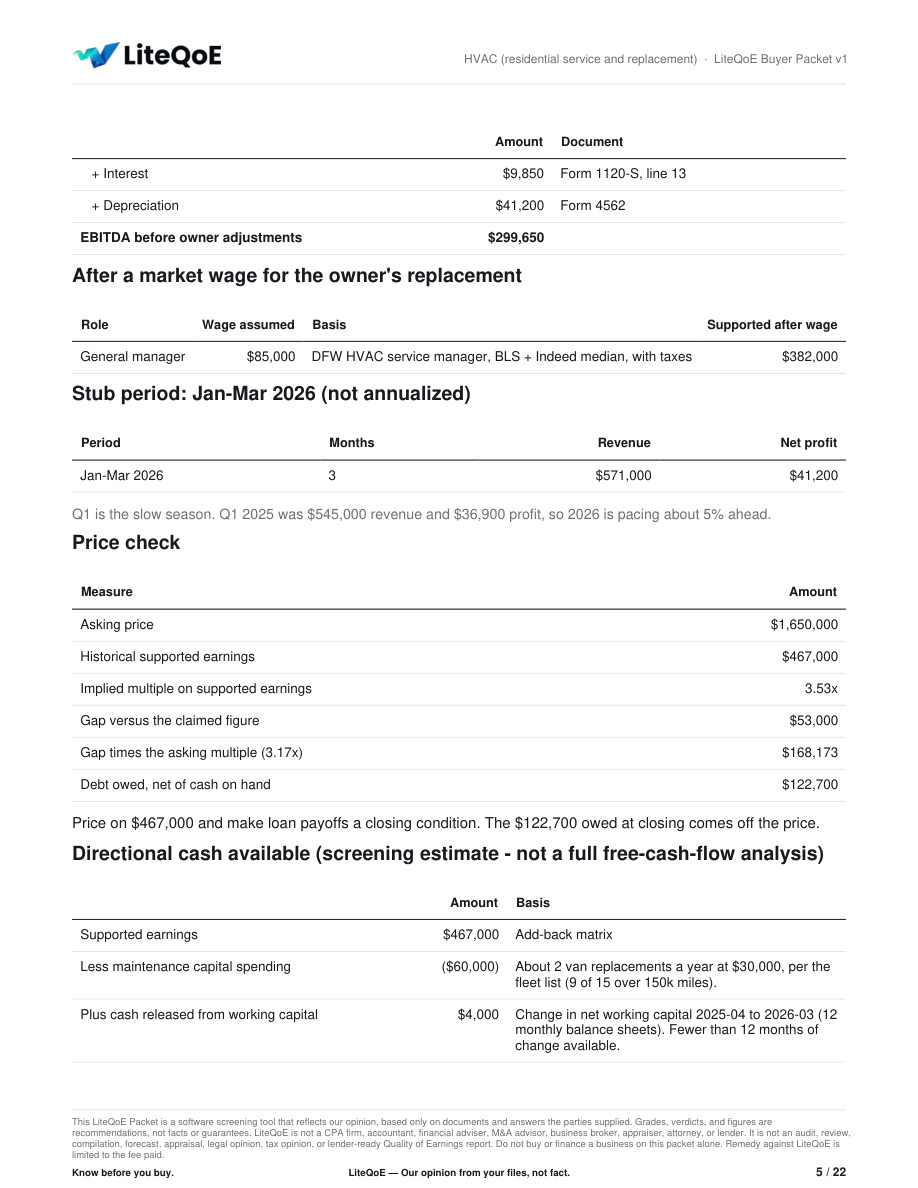
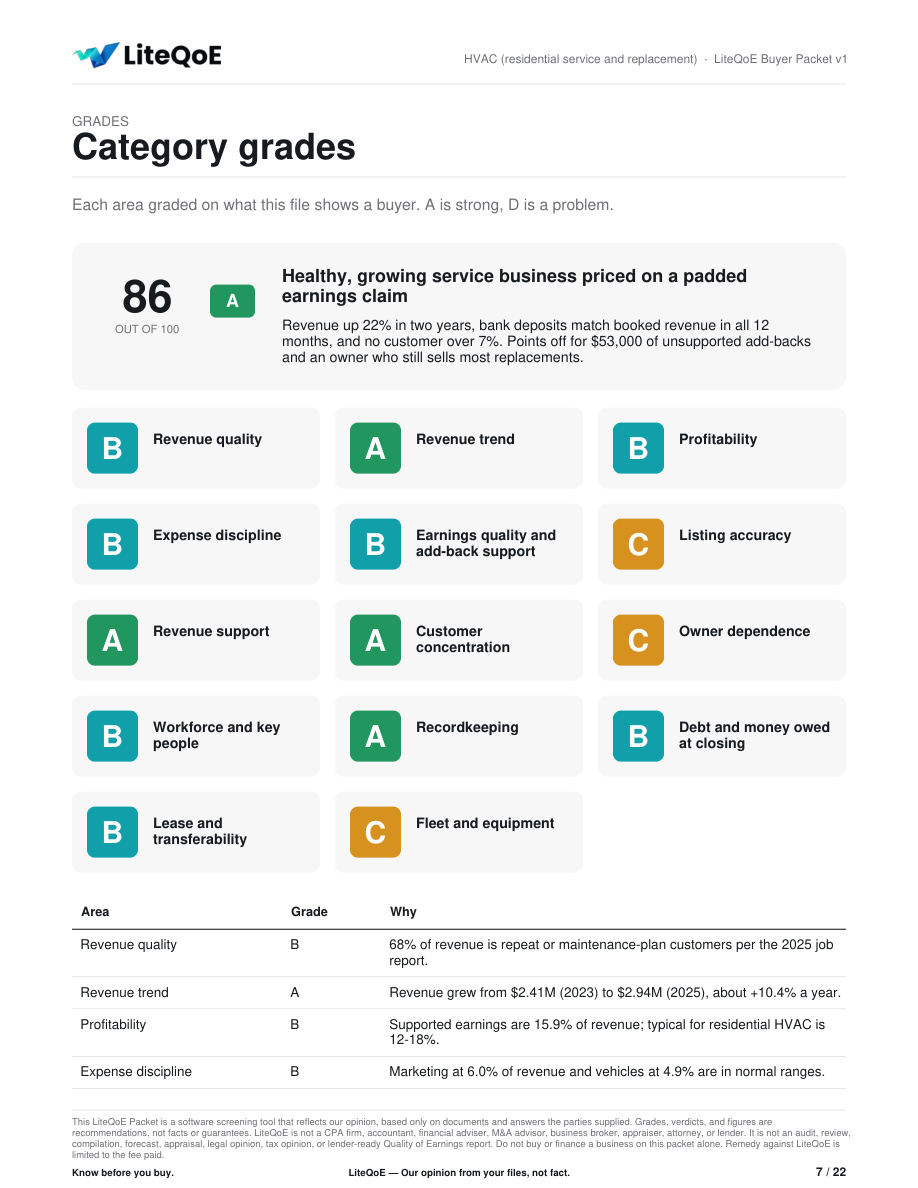
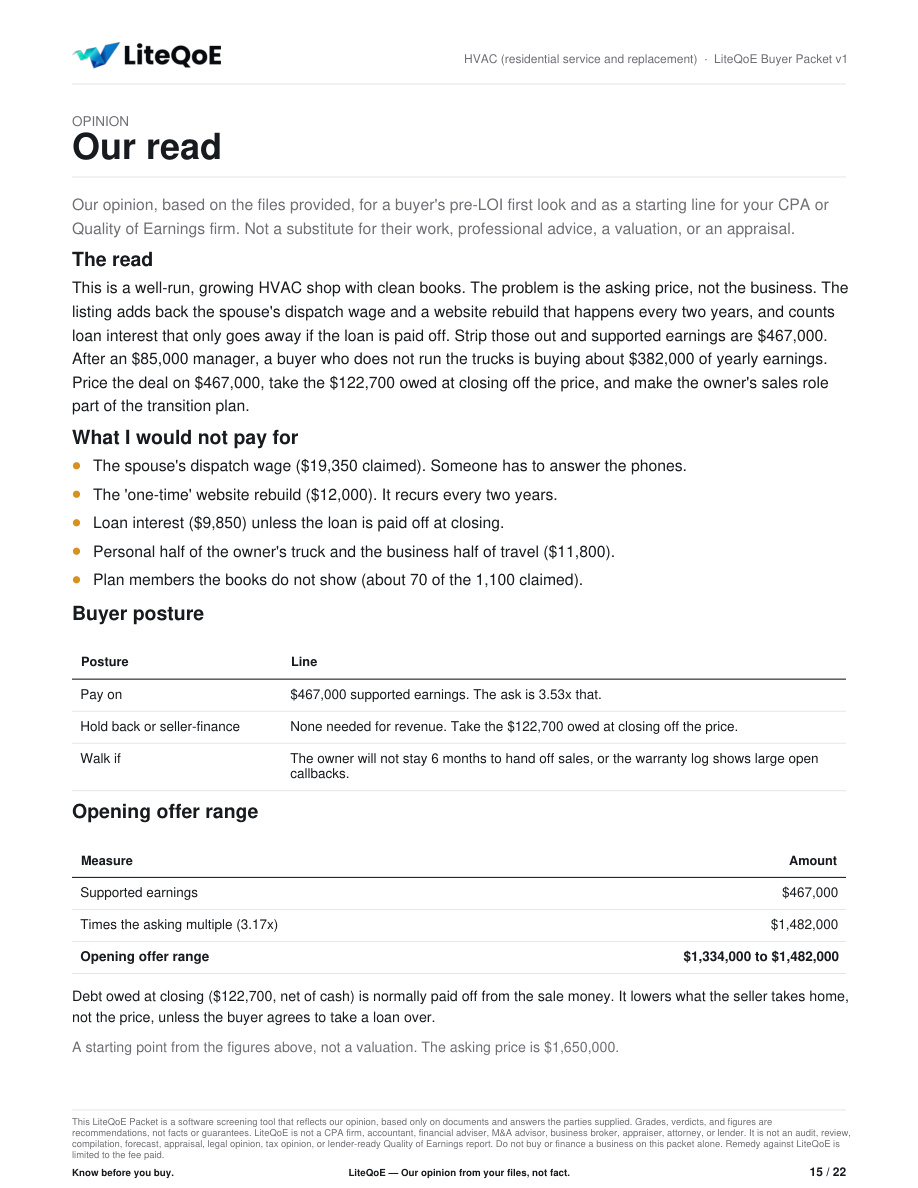
An SBA loan with a seller note sets the pace here: the lender's QoE, valuation, and credit approval usually take 6-8 weeks. Two open items from the screen, the unsupported $38,000 add-back and the equipment loan, should be settled before the purchase agreement is final.
LOI signed and kickoff
Week 1- Sign the LOI and confirm the exclusivity end dateBuyer, seller
Your 60-day window is the clock for everything below.
Done when: Signed LOI saved and dates on your calendar
- Send the diligence request list to the brokerBuyer
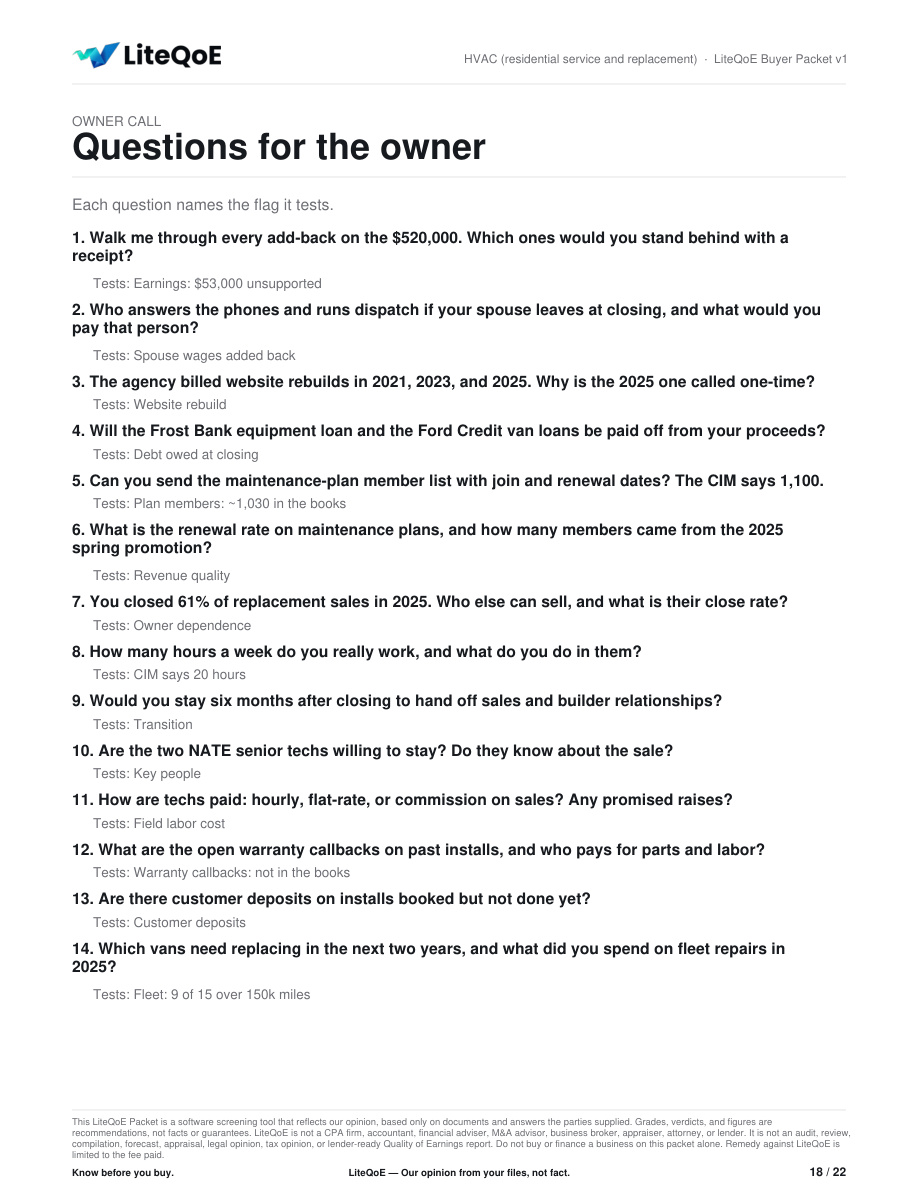
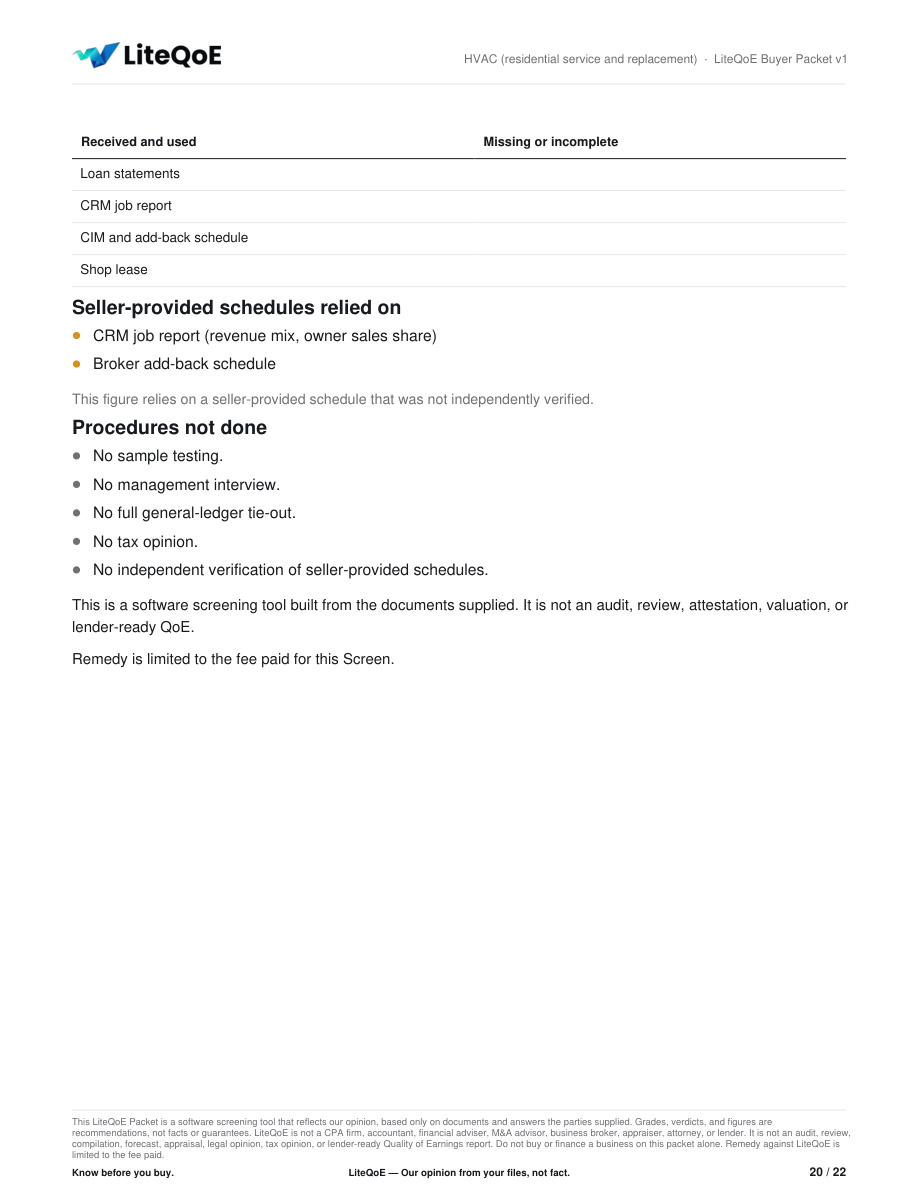
The screen flagged missing 2025 monthly bank statements and AR aging.
Done when: Broker confirms a delivery date
- Engage a deal attorney and a CPABuyer
Both need lead time; ask your attorney about entity setup now.
Done when: Engagement letters signed
Financial due diligence and CPA work
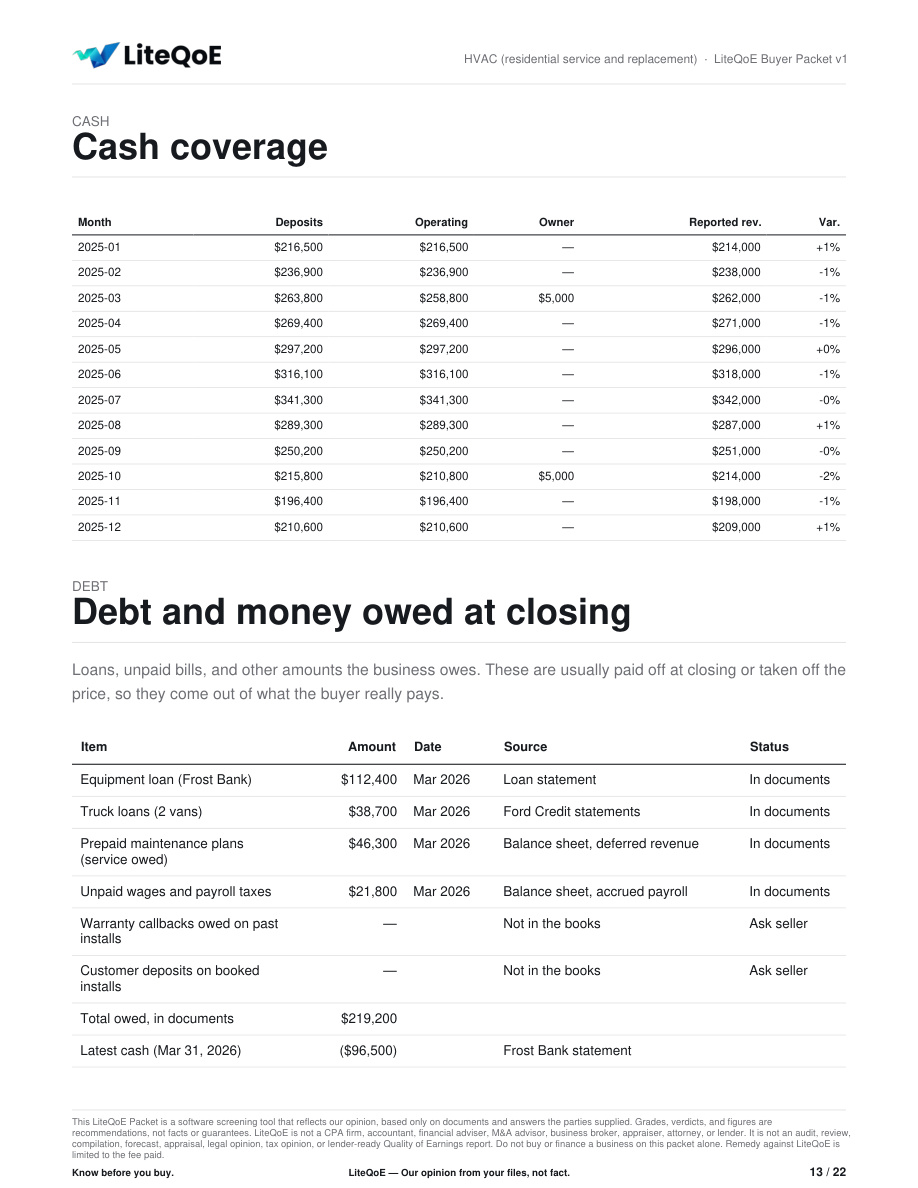
Weeks 1-4- Tie 24 months of bank deposits to reported revenueCPA
The screen read only 10 months of statements, so cash is not confirmed.
Done when: Variance under 3% or explained
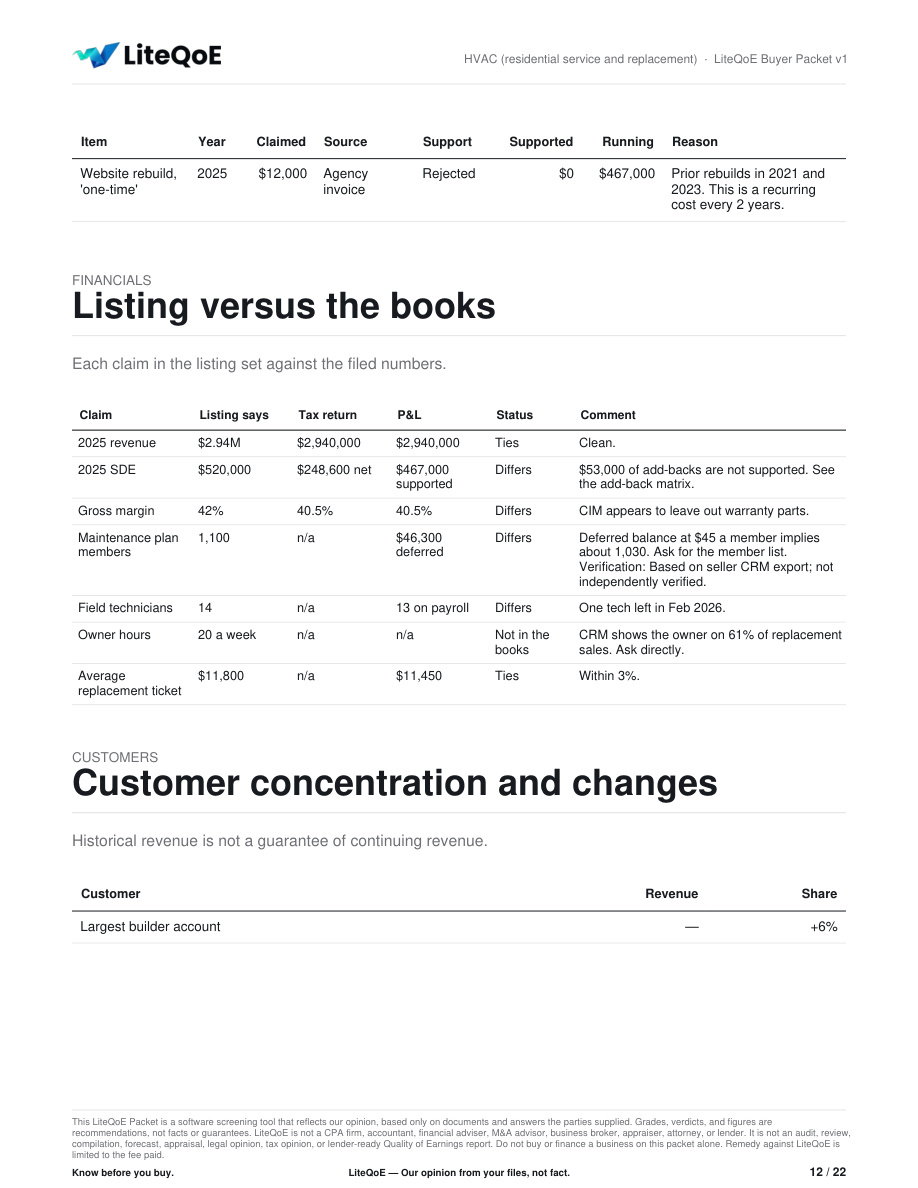
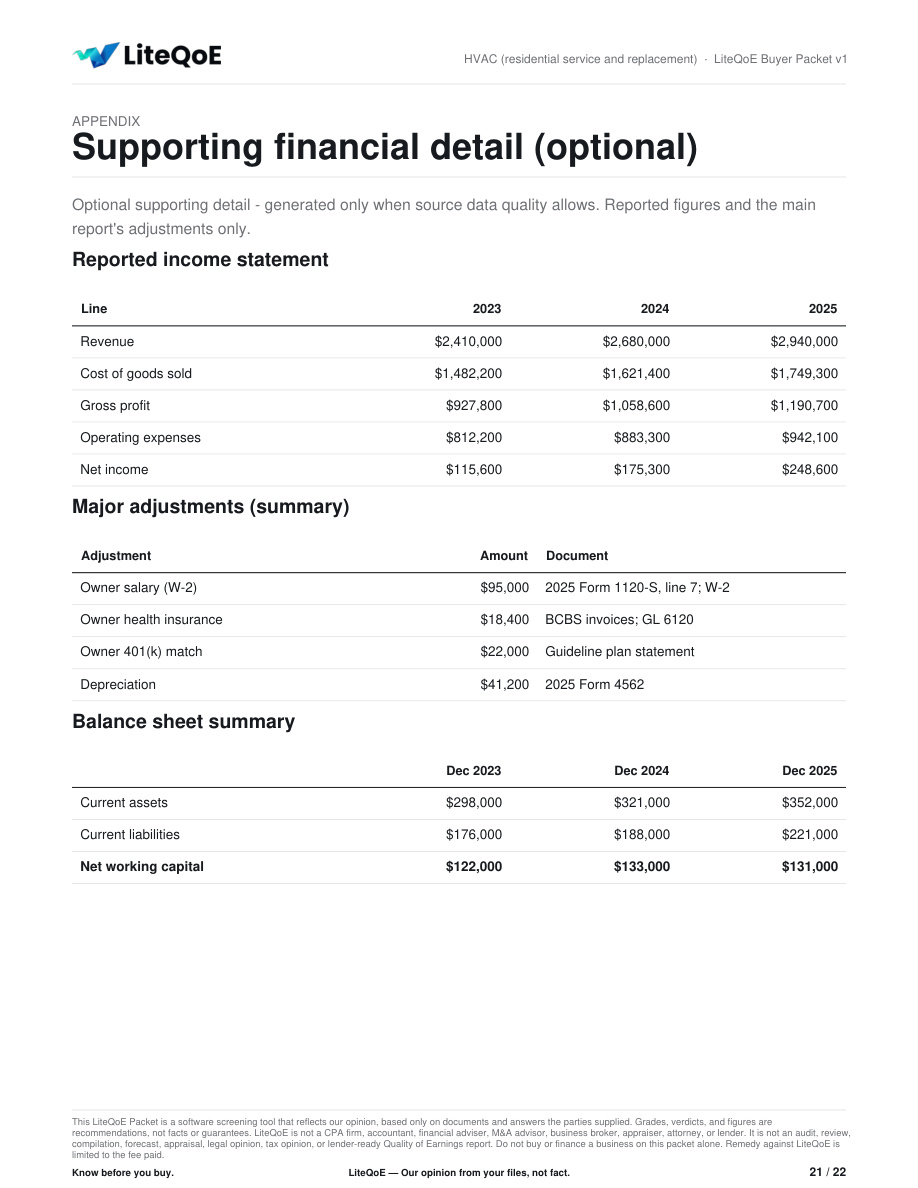
- Get proof for the $38,000 owner vehicle add-backSeller, CPA
Rejected on the screen for lack of support; it moves price by about $106,000 at the asking multiple.
Done when: Titles and mileage logs received, or add-back dropped
- Review AR aging and the top five customer contractsBuyer
Top customer is 22% of revenue.
Done when: Contract terms and renewal dates documented
Financing application and lender QoE
Weeks 2-8- Submit the SBA 7(a) application packageBuyer, lender
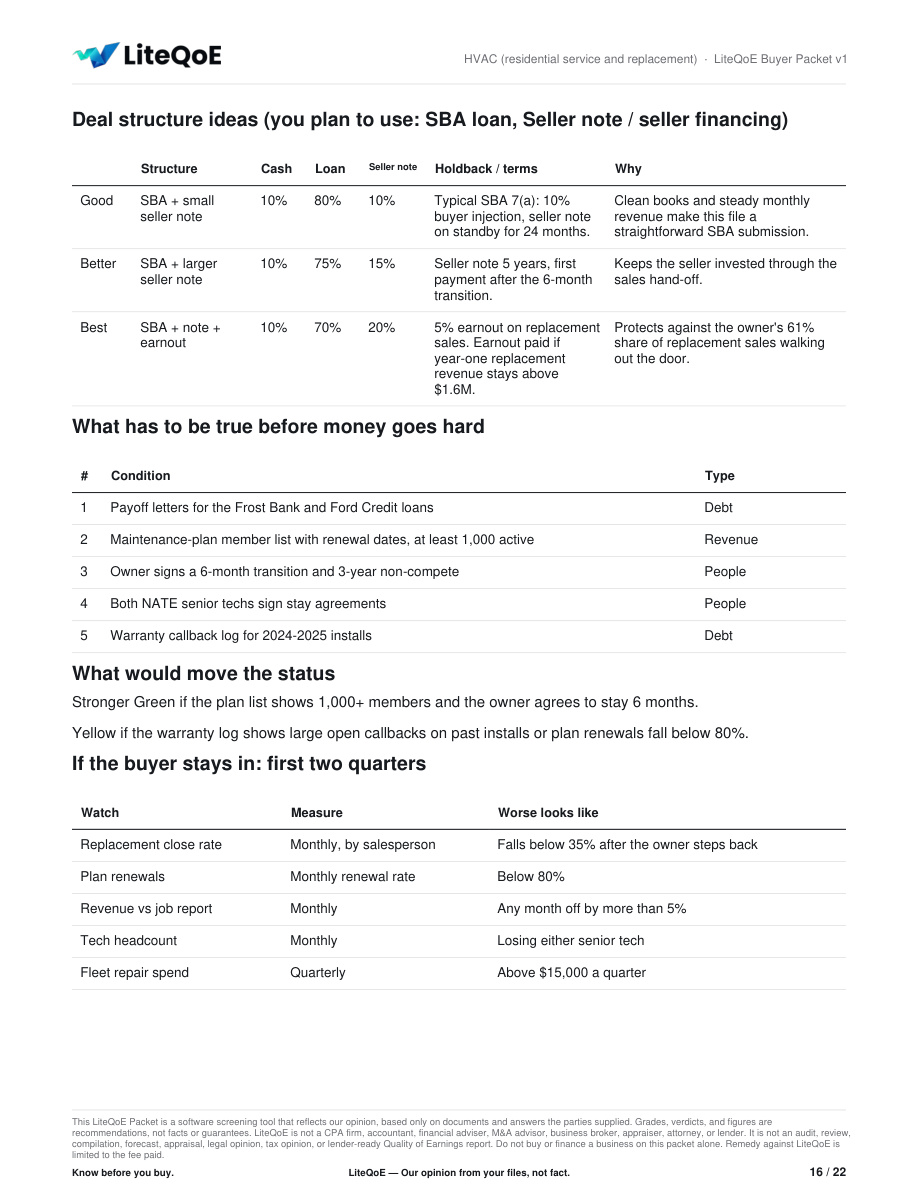
You chose SBA plus a seller note.
Done when: Lender confirms the file is complete
- Prove your equity injectionBuyer
SBA lenders often ask for 10% down, sourced and seasoned.
Done when: Bank statements accepted by the lender
- Support the lender-ordered QoE and business valuationQoE firm, seller
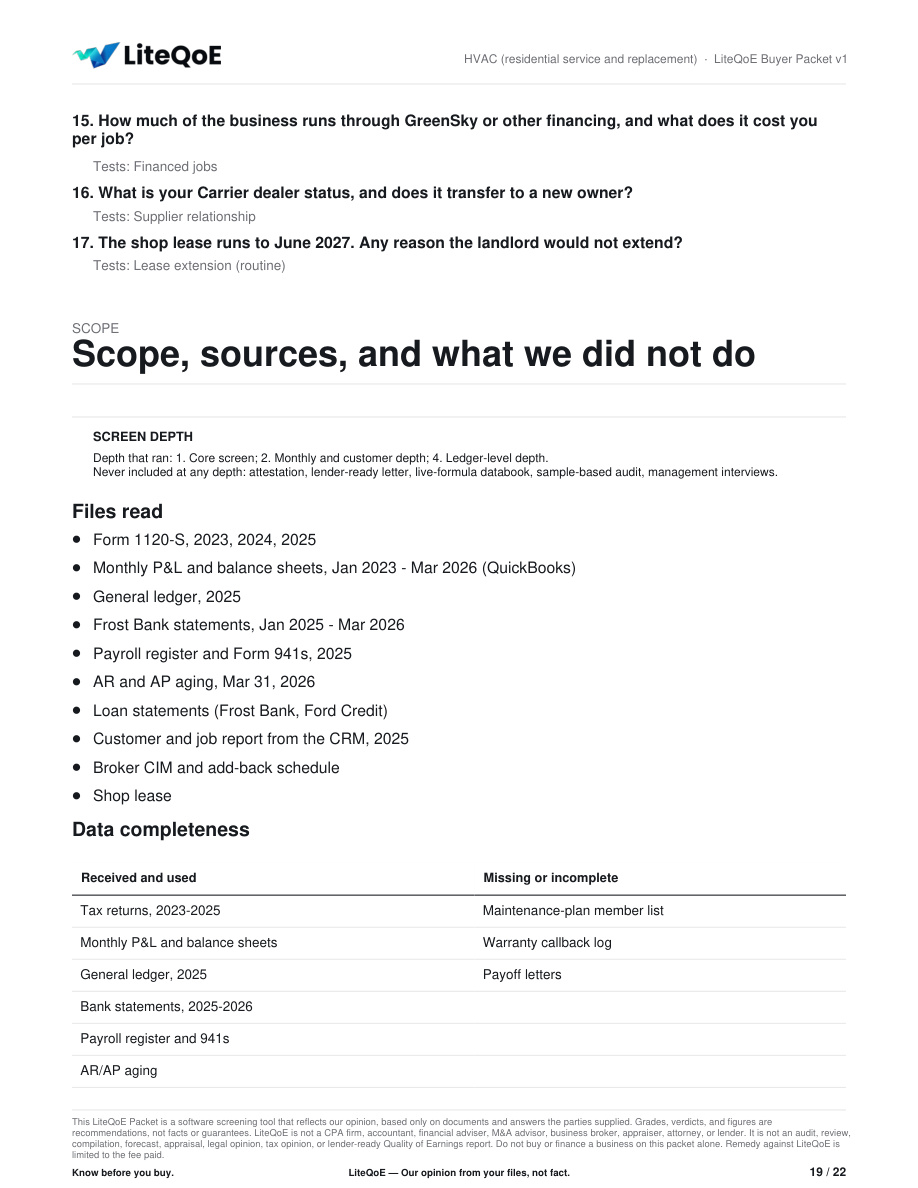
This screen is not lender-ready; the lender orders its own.
Done when: QoE and valuation reports delivered
- Agree seller note terms and any standby periodBuyer, seller, lender
SBA rules often put the seller note on standby.
Done when: Note terms in the term sheet
Operations, people, and lease
Weeks 3-8- Ask the landlord for a lease assignment or new leaseSeller, landlord
The lender usually needs lease term to cover the loan.
Done when: Signed assignment or letter of intent from landlord
- Confirm technician licenses transfer or stayBuyer
The owner holds the state contractor license.
Done when: Licensing path agreed in writing
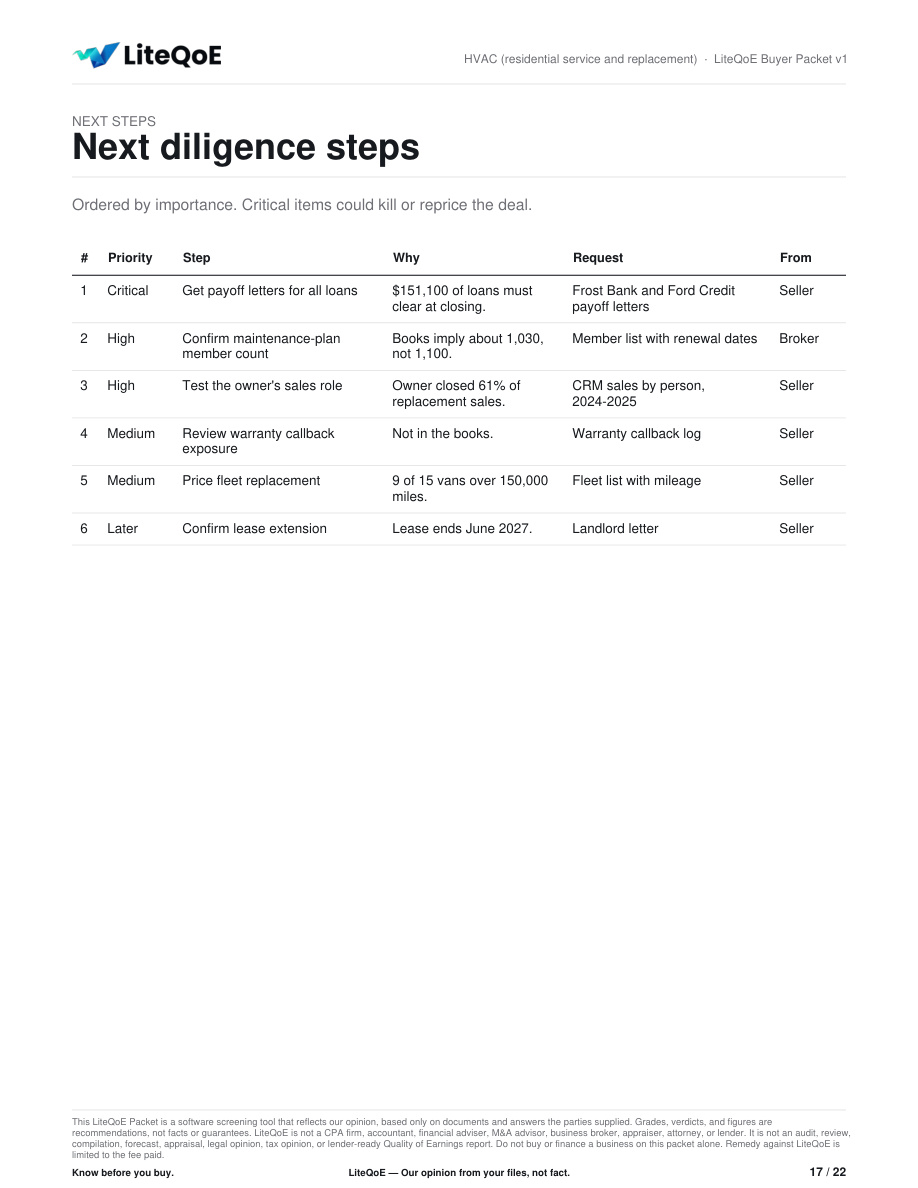
- Get payoff letter for the equipment loanSeller
Listed as a $64,000 debt-like item on the screen.
Done when: Payoff letter in hand
Purchase agreement and redlines
Weeks 6-11- Draft the asset purchase agreementAttorney
Start once diligence findings are mostly in.
Done when: First draft to seller's attorney
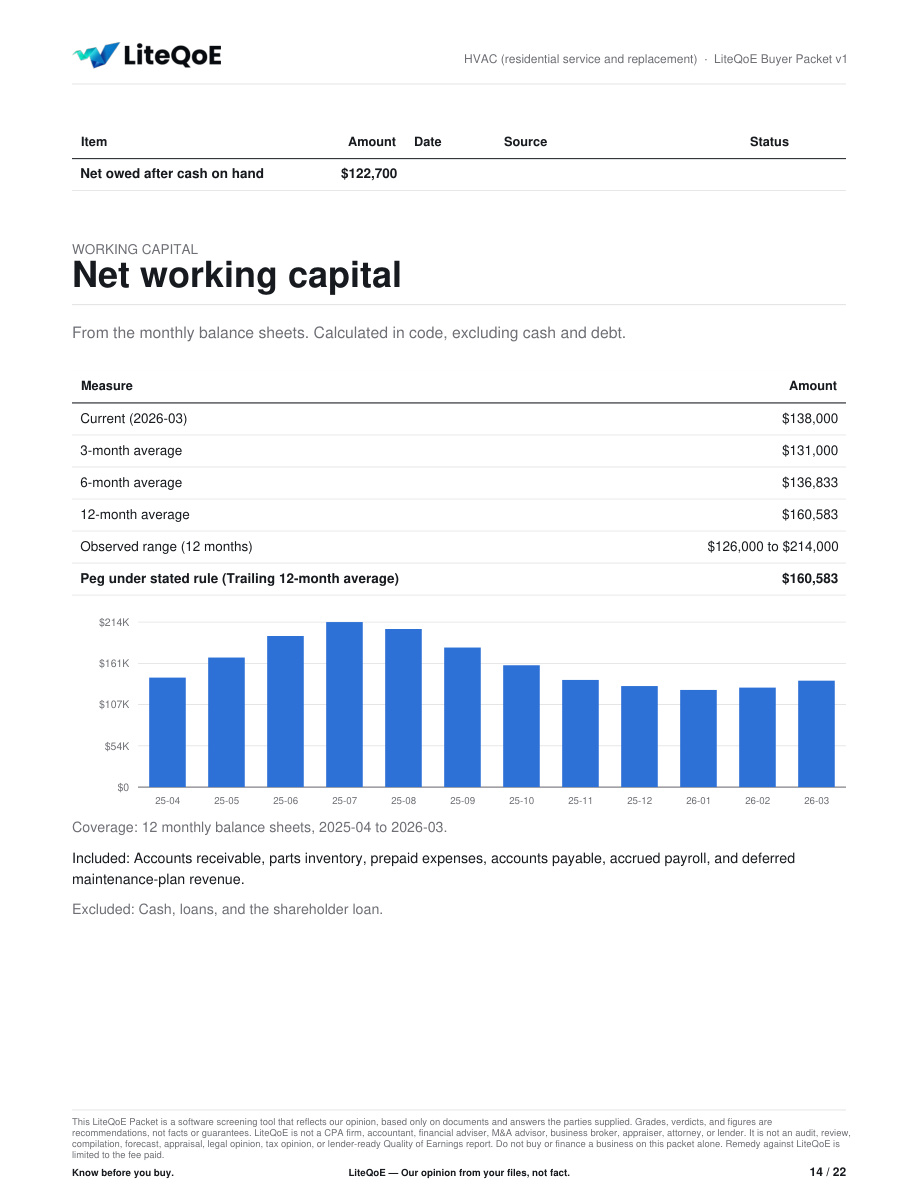
- Redline reps, warranties, and the working capital pegAttorney, buyer
Ask your attorney how to cover the open add-back and AR issues.
Done when: Both sides sign off on final draft
- Review disclosure schedules line by lineBuyer, attorney
Schedules are where surprises hide.
Done when: Schedules final and attached
Approval and closing prep
Weeks 10-14- Receive final loan approval and commitment letterLender
Nothing closes without it.
Done when: Commitment letter signed
- Bind insurance and open business bank accountsBuyer, insurance agent
Lenders require coverage at closing.
Done when: Certificates sent to the lender
- Plan the owner transition and employee announcementBuyer, seller
Owner runs dispatch and key accounts today.
Done when: Written 90-day transition plan
Closing and day one
Weeks 12-16- Do the final walkthrough and inventory countBuyer, seller
Confirms assets match the agreement.
Done when: Count signed by both sides
- Approve the funds flow memo and sign closing documentsAttorney, lender, buyer
Check every payoff on the memo, including the equipment loan.
Done when: Funds wired and keys handed over
Watch closely on this deal
- Bank statements for 2024 are still missing; lender QoE will need them.
- Top customer at 22% of revenue — ask for a meeting before closing.
- Owner holds the contractor license; plan the transfer early.
- The $38,000 vehicle add-back may not survive the lender's QoE.
Planning guide built from a screening analysis. Not legal, tax, or lending advice. Not a Quality of Earnings. Real dates depend on your lender, lawyer, CPA, and the seller. Confirm every step with them.